
Why ISD and Cross-Charge Continue to Confuse Enterprises
Let us take an example: a business organization has its head-office in Delhi and other branches in Ahmedabad, Hyderabad, and Delhi. Every month, the headquarter issues invoices for consulting, audit costs and software subscriptions among other shared services.
The finance team then poses the same question: should these expenditures be routed through ISD or Cross-Charge? In the case of most enterprises, there is no clear answer. The question about ISD vs cross charge is one of the most misunderstood dimensions of GST compliance.
Both mechanisms include spreading the cost among the locations of the business and both are concerned with the treatment of the GST of shared expenses. But they are fundamentally different in what they do and when they are applied. It’s not a minor bookkeeping issue to get this wrong.
Incorrect classification causes ITC claims to be rejected, tax authorities to issue notices, and makes conducting audits complicated. This blog illustrates the difference in easy-to-understand language and helps you decide which mechanism applies in your situation.
The Business Problem Both Mechanisms Are Trying to Solve
Large organisations rarely operate from a single location. Most have a head office managing group-level functions and branch offices running local operations. This structure creates two distinct types of shared costs.
The first type is expenses the head office pays on behalf of the entire business. A single invoice for a pan-India software licence or a group audit covers all locations, but the invoice arrives only at the head office.
The second type is services the head office provides to branches. The central HR team recruits for all locations. The corporate finance team manages treasury for the entire group. The IT department supports every office.
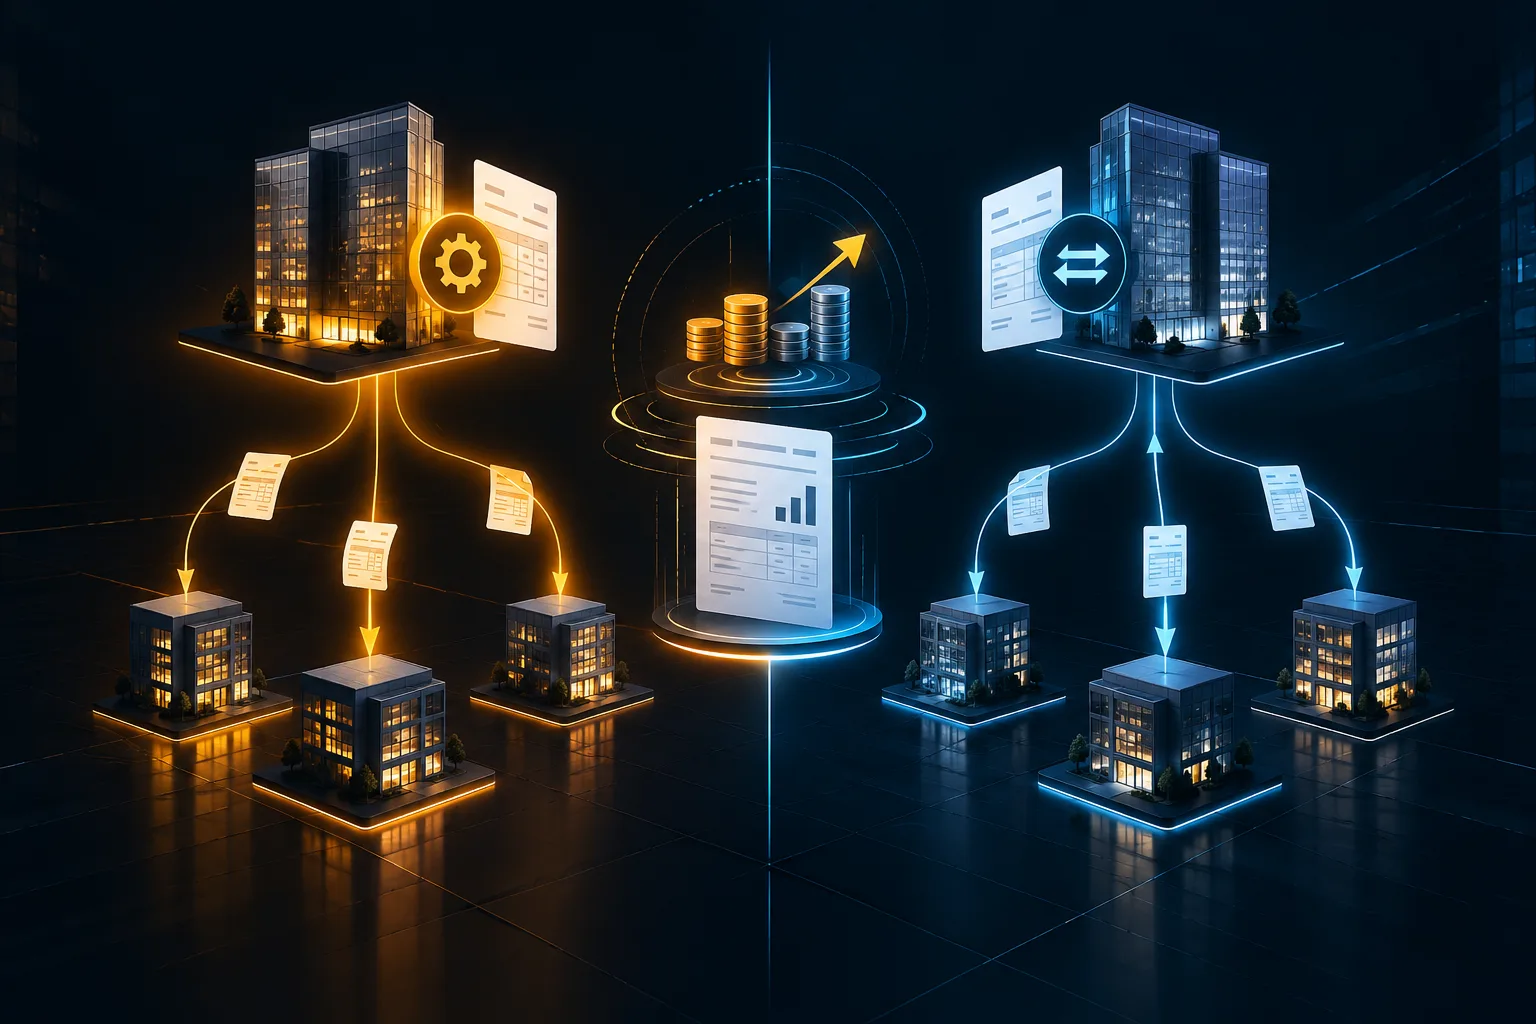
Both situations require cost allocation across GST registrations. But each calls for a different mechanism. ISD handles the first type. Cross-Charge handles the second. This is the core distinction that resolves most of the confusion.
What is ISD?
ISD stands for Input Service Distributor. It is a GST credit-sharing mechanism.
When the head office receives a single invoice covering services used by multiple branches, it gets the full input tax credit on that invoice. But the credit belongs to the business, and each branch that uses the service is entitled to its share. ISD allows the head office to distribute this ITC to the relevant branches in a structured, compliant way making ISD compliance solution important for multi-registration enterprises.
The key point: ISD is about distributing tax credit, not billing for services. The head office is not charging the branches for anything. It is simply passing on the GST credit they are entitled to.
For ISD to work, the distributing office needs a separate ISD registration under GST. It then issues ISD invoices to recipient branches, specifying each branch’s GSTIN and the credit being distributed.
Common expenses typically processed through ISD:
- Enterprise software subscriptions (ERP, HRMS, cloud tools)
- Statutory audit and certification fees
- Corporate insurance premiums
- Group-level consulting and advisory fees
- Common marketing and brand expenses
What is Cross-Charge?
Cross-Charge applies when one part of a business actively provides services to another part.
Under GST, a supply of services between two different registrations of the same legal entity is treated as a taxable transaction. So, when the head office’s finance team works for a branch, or the central IT team supports all offices, those are considered internal supplies. The head office must raise a tax invoice to the branch for these services and charge applicable GST.
Think of it this way: the head office is acting as an internal service provider to the branch. Even without an external commercial contract, GST law requires this internal transaction to be documented and taxed properly.
The receiving branch can claim ITC on the GST charged through Cross-Charge, provided it is used for business purposes. This keeps the overall tax cost neutral for most enterprises, but only if the transaction is properly documented.
Common situations where Cross-Charge applies:
- Head office finance and accounts team supporting branch operations
- Central HR managing recruitment, payroll, or training for multiple locations
- Corporate IT providing helpdesk or infrastructure services across offices
- Senior management time allocated to branch businesses
- Legal and compliance functions supporting all registrations
ISD vs Cross-Charge: Key Differences briefly
Here is a quick reference comparison. This is where the GST cross charge vs ISD distinction becomes most useful in practice.
| Factor | ISD | Cross-Charge |
| What it does | Distributes GST credit from a shared invoice | Bills for an internal service one location provides to another |
| Nature | Transfer of input tax credit (ITC) | Taxable supply of internal services |
| Who raises the document | ISD office raises ISD invoice | Supplying location raises a tax invoice |
| Registration needed | Separate ISD registration at distributing office | Regular GST registration of the supplying location |
| Common examples | Software licence, audit fees, insurance | HO finance team, central HR, IT support |
The simplest rule of thumb: if there is a common external invoice and a tax credit to share, think ISD. If the head office is doing work for branches and providing a service, think Cross-Charge.
Common Mistakes Enterprises Make
Treating them as interchangeable
Many businesses pick one method and apply it to every situation. Some run all shared costs through Cross-Charge without ever setting up ISD. Others distribute everything through ISD, including internal services that should go through Cross-Charge. Both approaches create compliance gaps which is why understanding common ISD distribution errors is important before deciding how shared credits should be allocated.
Poor documentation
ISD invoices must clearly state the GSTIN of each recipient branch and the credit being distributed. Cross-Charge invoices must reflect a real, supportable value for the services provided. Vague or missing documents are the most common trigger for disputes during audits.
Inconsistent allocation methods
The cost allocation methodology must be consistent and defensible. Whether you use headcount, revenue, floor space, or actual usage, the formula must stay the same across periods. Changing bases frequently without documentation creates audit risk.
Manual tracking at scale
Teams tracking ISD and Cross-Charge through spreadsheets frequently miss filing deadlines, miscalculate credit distributions, or fail to match ISD invoices with GSTR returns. Manual processes do not scale across 20 or more GST registrations making ISD compliance automation increasingly important for large enterprises.
Delayed allocations
ITC distributed through ISD must be reflected in the correct return period. Late processing means the recipient branch loses the credit for that period, which affects working capital. Cross-Charge invoices raised late can also cause GSTR-2B mismatches.
How to Build a Scalable Compliance Process
The complexity of ISD and Cross-Charge with multiple registrations is real, but it’s manageable with the right approach. Start by writing down your allocation policy for each type of shared cost.
Determine if you’re sharing by headcount, revenue, or usage, and use that formula every month. Assign clear ownership so that these tasks don’t get lost in the shuffle close to filing deadlines. Centralised visibility matters. Without a system that tracks which invoices have been received, which need ISD distribution, and which Cross-Charge invoices were raised and matched, the process becomes error-prone at scale.
Nowadays, GST compliance platforms can automate the identification of ISD-eligible invoices, calculate distribution amounts, generate compliant ISD invoices, and reconcile Cross-Charge entries with GSTR returns.
At Cygnet, our ISD module is designed for organizations with multiple registrations. It comes with an ERP integration; the allocation process is automated so that you can get your compliance audit ready without the manual work. Review your ISD and Cross-Charge practices at least once a year. Business structures change, new services are added, and allocation bases may need to be updated.
Conclusion
The debate around ISD vs cross charge often exists because businesses treat them as alternatives. In practice, they solve two different problems.
ISD helps enterprises distribute eligible input tax credit from shared invoices across their GST registrations. Cross-Charge helps enterprises account for internal services that one location provides to another. Using both correctly, in the right situations, is what builds a clean and audit-ready GST operating model.
As Indian businesses expand to more locations, and shared service models grow more complex, accurate GST cross charge vs ISD treatment becomes increasingly important. Enterprises that get this right today will face fewer compliance surprises, smoother audits, and a more efficient finance operation going forward.
FAQ's
No. ISD and Cross-Charge are not interchangeable. If the transaction involves distributing input tax credit from a common service invoice, ISD should be used. Cross-Charge applies only when one GST registration provides services to another registration within the same organisation.
ISD is generally used for common service expenses such as software subscriptions, statutory audit fees, insurance premiums, consulting services, and other shared costs incurred for multiple GST registrations. These expenses allow the input tax credit to be distributed to the eligible branches.
Author

Kesha Shah
General Manager - Products Marketing
Kesha Kumar leads the global products marketing team at Cygnet.One, where she turns the complexity of tax and finance transformation into stories that resonate with the people who matter most. She’s the strategic force behind the brand’s presence across India, the GCC, Southeast Asia, and Europe, translating dense subjects like e-Invoicing mandates, digital engineering, and enterprise AI into narratives that inform and drive action. With expertise spanning tax and finance transformation, quality, enterprise applications, and data and AI, Kesha blends sharp strategic thinking with a marketer’s instinct for what truly connects. At Cygnet.One, she does more than build campaigns and content; she shapes the conversations that help enterprises navigate compliance with clarity and confidence, propelling the brand to the forefront of the industry along the way.